 by INVESTO CONSULTING GROUP +919999077799 +918750000081
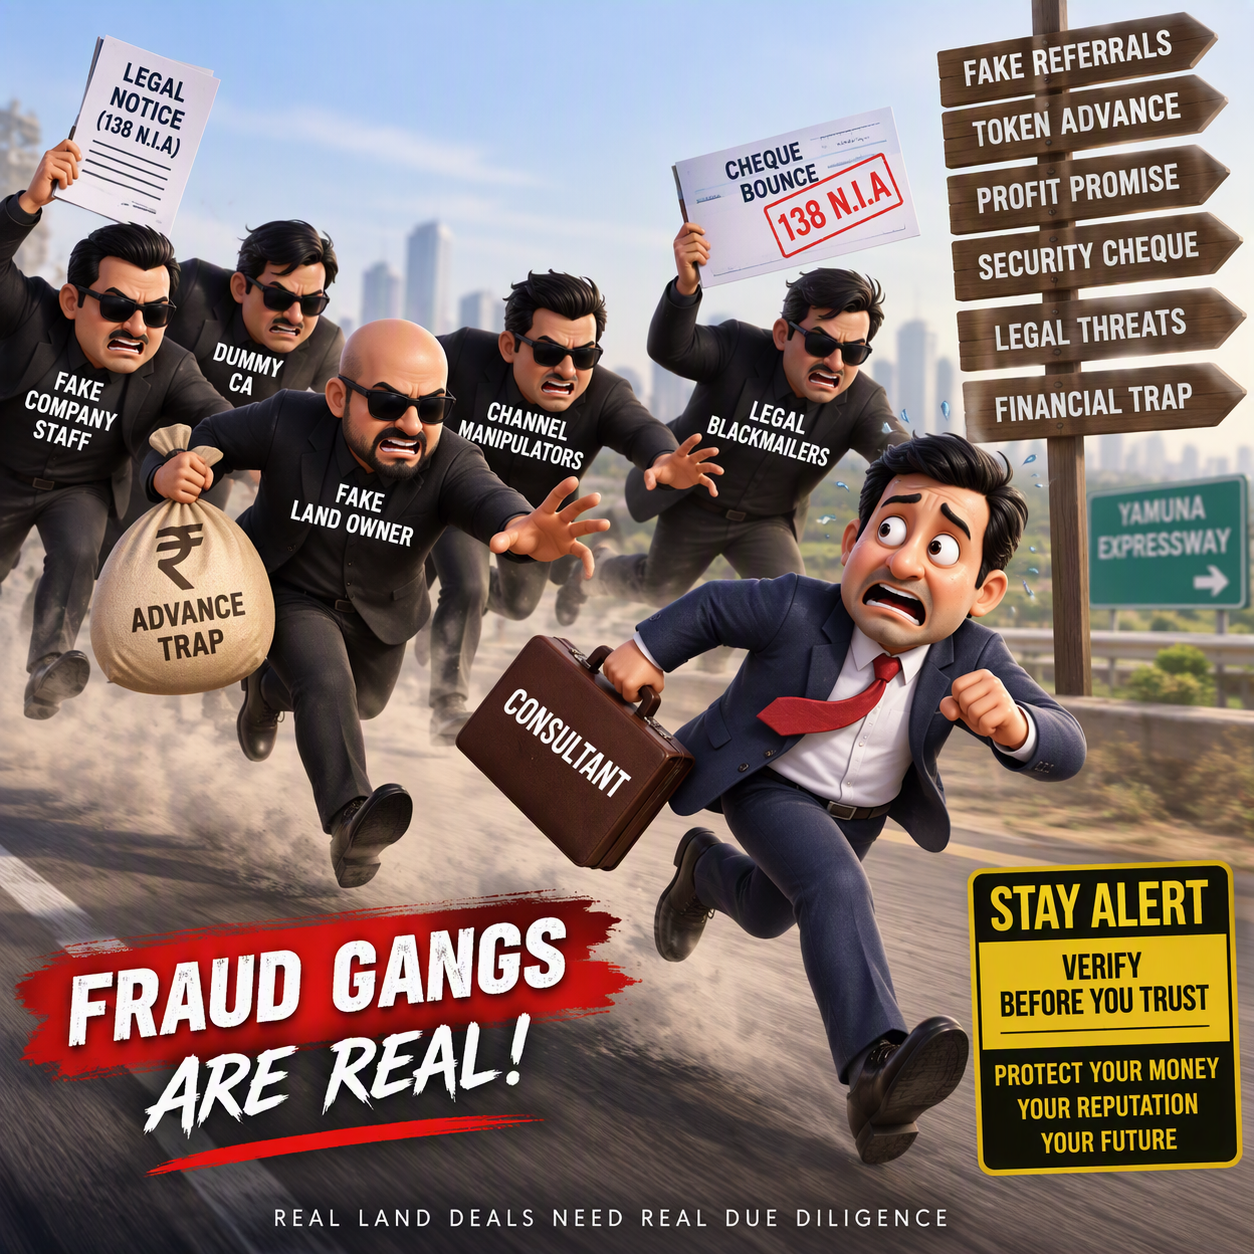
A Real Estate Industry Case Study from the Yamuna Expressway Region
Disclaimer: This article is based on a specific transaction experience and reflects observations, red flags, and suspected patterns identified during the course of negotiations. The article does not allege criminal liability against any specific individual or entity unless determined by a competent court of law. It is intended as an educational and industry-awareness document for consultants, brokers, channel partners, investors and real estate professionals.
Introduction: When a ₹22.5 Crore Land Deal Turns Into a Fraud Investigation
India’s real estate sector runs on relationships.
Deals worth crores often begin with a phone call, a trusted reference, a meeting over tea, or an introduction made by a known channel partner. Unlike stock exchanges and regulated financial markets, large land transactions still depend heavily upon personal credibility and network trust.
Unfortunately, fraudsters understand this better than anyone else.
Our team recently encountered what appeared to be a sophisticated white-collar fraud model revolving around the proposed acquisition of approximately 9 Bigha Abadi land near the Yamuna Expressway corridor surrounding a reputed university area. The indicative value of the transaction was approximately ₹22.5 crore.
At first glance, everything appeared genuine.
There was land.
There was a farmer.
There was a buyer.
There was a company.
There were senior executives.
There were lawyers.
There were site visits.
There were negotiations.
There was even token money.
But as our legal team began examining the structure of the deal, a shocking possibility emerged.
The transaction may never have been designed to buy land.
Rather, the land appeared to be the bait used to create financial exposure for intermediaries and channel partners.
What emerged was a possible ecosystem involving false urgency, manipulated trust, security cheques, staged payments, advance forfeiture mechanisms and the potential use of cheque dishonour proceedings as pressure tactics.
This article decodes how such a model may operate and why every consultant, broker and investor must understand its warning signs.
Phase One: The Trusted Referral
The story began with what seemed like the most trustworthy source possible.
Our team received a call through an existing network channel from Dehradun, Uttarakhand.
The reference came from within a professional circle.
Nothing appeared suspicious.
The inquiry involved two senior staff members representing a company that reportedly intended to acquire land for its owner.
The proposed acquisition value was approximately ₹22.5 crore.
The executives explained an interesting business challenge.
If their company purchased the land directly from the owner, they would not earn anything personally.
Instead, they wished to create a structure where a consultant or intermediary would first acquire control over the property and subsequently resell it to the company at a mutually agreed margin.
Such arrangements are not uncommon in the Indian real estate market.
Several land aggregation deals operate through assignment structures, intermediary acquisitions and value-added resales.
On paper, the proposal appeared commercially reasonable.
Phase Two: The Consultant Is Brought In
The company representatives approached our team seeking support in executing the transaction.
The proposal was simple:
- Identify and negotiate the land.
- Execute the acquisition structure.
- Facilitate the resale.
- Receive a professional consultancy fee.
A standard market consultancy fee of 1% was agreed.
Based on a ₹22.5 crore transaction, the consultancy compensation itself was substantial.
To demonstrate seriousness, the representatives paid approximately ₹15 lakh as a token commitment.
From a consultant’s perspective, this signaled intent.
Generally, fraudsters do not begin by paying money.
Or at least that is what most people think.
This payment became one of the strongest credibility-building tools in the entire transaction.
At the time, nobody suspected that the payment itself could potentially be part of a larger strategy.
Phase Three: The Farmer and the Advance Requirement
The identified land belonged to a reputed local farmer.
Meetings were organized.
The land was inspected.
Negotiations took place.
The farmer’s position was straightforward.
For proceeding with the sale, he demanded advance consideration.
Two options were presented.
Option One
Approximately 10% advance, amounting to nearly ₹2.2 crore.
Against this amount, a notarized receipt would be issued.
Option Two
Approximately 25% consideration.
Against this, stronger registered documentation could be executed.
These demands were not unusual.
In high-value land transactions, serious sellers often insist on substantial deposits before taking property off the market.
Everything still appeared normal.
The deal appeared alive.
The buyer appeared serious.
The seller appeared committed.
The consultant appeared protected.
Then the script suddenly changed.
The Five-Star Hotel Meeting
One of the most critical moments occurred during a meeting at a five-star hotel in Greater Noida.
The two company representatives met our team along with the farmer.
During the meeting, approximately ₹15 lakh was handed to the farmer as advance consideration.
A simple receipt was prepared.
The meeting concluded positively.
The atmosphere was optimistic.
Everybody believed the transaction was moving forward.
At that point there was no obvious reason to suspect anything unusual.
The next day, however, a completely different conversation began.
The Real Proposal Finally Appears
When the company representatives returned, they brought a new problem.
They claimed they were unable to arrange the balance amount required for completing the 10% advance payment.
According to them, nearly ₹2.05 crore still needed to be arranged.
Then came the proposal that changed everything.
They requested assistance from our side.
Specifically, they asked for:
- Cash support of approximately ₹15 lakh.
- A cheque ranging between ₹60 lakh to ₹80 lakh.
- Financial participation in the advance payment.
Their reasoning sounded convincing.
They claimed that if all parties jointly contributed toward the advance, the property could be secured.
Upon resale to their company, an expected profit of approximately ₹2 crore would be generated.
That profit would then be divided among the three participants.
The security cheque, they assured us, was only temporary.
The cheque would later be exchanged against cash.
No risk existed.
No liability would remain.
Everyone would profit.
This is where many professionals make fatal mistakes.
The language of consultancy suddenly changes into the language of partnership.
Understanding the Transition from Consultant to Victim
One of the most dangerous moments in any fraudulent transaction occurs when a consultant stops being a consultant.
As long as you remain an advisor, your exposure is limited.
The moment you become:
- A financier
- A guarantor
- A cheque issuer
- A partner
- A participant in profit sharing
your risk changes completely.
Our original role was consultancy.
Yet the proposed structure was quietly pushing us toward financing and guaranteeing a transaction.
That transition became the most important red flag identified by our legal advisors.
The Legal Team Begins Investigation
Fortunately, our legal team reviewed the transaction before any additional commitments were made.
What they discovered was deeply concerning.
Instead of analyzing the property, they analyzed the behaviour of the parties.
Instead of asking whether the land existed, they asked a more important question:
Who benefits if the transaction fails?
That question changed everything.
In a genuine transaction:
Everybody benefits from completion.
In a fraudulent structure:
Certain participants may actually benefit more from failure than success.
The legal team began connecting multiple observations.
The pattern was disturbing.
The Suspected Fraud Ecosystem
The suspected model appeared larger than a single transaction.
It looked more like an ecosystem.
An ecosystem where multiple participants appeared to play different roles.
Potential participants could include:
- The seller
- Company staff
- Financial advisors
- Local coordinators
- Channel connectors
- Documentation handlers
- Associated professionals
Individually, none may appear suspicious.
Collectively, however, their actions seemed to support the same outcome.
The objective did not appear to be property transfer.
The objective appeared to be financial entanglement.
The Mystery of the ₹15 Lakh Advance
One fact particularly troubled the legal team.
The initial ₹15 lakh payment appeared designed to generate confidence.
Every consultant naturally thinks:
“Nobody intending fraud would willingly part with ₹15 lakh.”
But experienced fraud operators understand human psychology.
A relatively small amount invested initially can create trust worth crores later.
Even more concerning was a possibility suggested during the review.
If the advance amount eventually returns through back-channel arrangements, then the payment may never have represented an actual financial sacrifice.
It becomes a credibility investment.
A marketing expense for a much larger extraction strategy.
The Importance of the Security Cheque
The legal team focused heavily on the requested cheque.
Why was the cheque so important?
Why not simply wait for corporate funding?
Why not arrange institutional finance?
Why was a consultant being asked to become a guarantor?
The answer may explain the heart of the alleged scheme.
A security cheque creates a legal instrument.
The moment a person voluntarily signs and hands over that cheque, a future dispute becomes possible.
The cheque itself becomes more valuable than the transaction.
In many suspected fraud models, the cheque is the real target.
Not the land.
Not the consultancy.
Not the acquisition.
The cheque.
The Alleged End Game
Based upon industry inputs and legal observations, the suspected sequence might operate as follows:
Stage 1
Identify a large transaction.
Stage 2
Use trusted referrals.
Stage 3
Create confidence through meetings, hotels and token payments.
Stage 4
Introduce a reputed land owner.
Stage 5
Create urgency around advance payments.
Stage 6
Encourage consultants to contribute funds.
Stage 7
Obtain security cheques.
Stage 8
Allow the transaction to collapse.
Stage 9
Trigger forfeiture clauses or payment disputes.
Stage 10
Present cheques for encashment.
Stage 11
Generate legal notices.
Stage 12
Seek settlements through pressure.
At this stage, the land has served its purpose.
The trap has already been completed.
How Channel Partners Become Easy Targets
The primary victims in such structures are often channel partners.
Why?
Because channel partners operate entirely on trust.
Their business depends upon reputation.
Fraudsters understand this perfectly.
A channel partner:
- Wants deals completed.
- Wants relationships preserved.
- Wants goodwill maintained.
- Wants disputes avoided.
These natural business instincts become weaknesses when facing an organized fraud ecosystem.
Once legal threats emerge, many intermediaries prefer settlement instead of litigation.
The fraudster understands this psychology.
Manufactured Failure: The Most Dangerous Concept
Perhaps the most important lesson from this case is the concept of manufactured failure.
In a genuine real estate deal, everybody seeks completion.
In a fraudulent model, completion may never be the objective.
Instead, failure itself becomes the product.
The transaction is structured to fail.
The advance remains incomplete.
Conditions remain unmet.
Funding never arrives.
Timelines expire.
Obligations are triggered.
Disputes emerge.
What appears to be an unsuccessful transaction may actually be a successful fraud operation.
Red Flags That Should Never Be Ignored
From this experience, several warning indicators emerged.
Red Flag 1
Buyer representatives lack purchasing capacity but seek high-value transactions.
Red Flag 2
Consultants are encouraged to become financiers.
Red Flag 3
Security cheques become central to discussions.
Red Flag 4
Profit-sharing opportunities suddenly appear.
Red Flag 5
Urgency overrides due diligence.
Red Flag 6
Documentation remains intentionally weak.
Red Flag 7
Cash transactions dominate the structure.
Red Flag 8
The same individuals benefit if the deal collapses.
Red Flag 9
Verbal commitments exceed written commitments.
Red Flag 10
Pressure is used to bypass legal review.
The Bigger Threat to the Indian Real Estate Industry
Cases like this represent more than isolated incidents.
They damage trust throughout the industry.
Every year, genuine investors become more cautious.
Legitimate brokers struggle to build confidence.
Real sellers face increased scrutiny.
Transaction cycles become longer.
The hidden cost of white-collar fraud is not merely financial loss.
It is the destruction of trust.
And trust remains the most valuable currency in Indian real estate.
Conclusion: The Deal Was Never the Deal
The most shocking lesson from this experience is that what appears obvious may not be real.
There was real land.
There was a real farmer.
There was a real company structure.
There were real meetings.
There were real payments.
There were real documents.
Yet behind those realities may have existed a far more dangerous objective.
A manufactured transaction designed to draw consultants and channel partners into financial commitments, issue security instruments, create legal exposure and ultimately force settlements through pressure.
If there is one lesson every real estate consultant, broker, land aggregator and investor should remember, it is this:
Never finance a transaction merely because you trust the people involved.
Never issue a cheque simply because someone promises it is only security.
Never move from consultant to participant without understanding the legal consequences.
And always ask one critical question: Who benefits if this deal fails?
Because in sophisticated white-collar frauds, the answer to that question often reveals the truth behind the entire transaction.
The land is merely the stage.
The transaction is merely the script.
The cheque is the weapon.
And trust is the commodity being traded.